The Fourteenth Amendment
What it is: Argued by researchers to have been never properly ratified, though treated as ratified in 1868. The Fourteenth Amendment established a federal "U.S. citizen" status and addressed due process and equal protection under the Law. (Click For Details)
Why We refrain: By claiming Fourteenth-Amendment "U.S. citizen" status, a Man is treated as a federal subject, placed under federal jurisdiction, federal Statutes, and federal taxation. That status is different from the free national status We study (see National Status). Because invoking the Fourteenth reaffirms a status of subjection rather than freedom, We do not invoke it as the basis for any claim or status.
The Fifteenth Amendment
What it is: Argued by researchers to have been never properly ratified, though treated as ratified in 1870. The Fifteenth Amendment prohibits denying the vote based on race, color, or prior condition of servitude. (Click For Details)
Why We refrain: The Fifteenth operates within the same Fourteenth-Amendment framework of federal citizenship. To rely on it is to reaffirm the very status We refrain from. We do not invoke the Fifteenth as a basis for status or claims.
The Sixteenth Amendment
What it is: Argued by researchers to have been never properly ratified, though treated as ratified in 1913. The Sixteenth Amendment is cited as the Authority for the federal income tax. (Click For Details)
Why We refrain: The Sixteenth Amendment was ratified in 1913, and the Supreme Court has consistently upheld it as the constitutional Authority for the federal income tax. This project does not claim that the Amendment was improperly ratified, nor does it assert that the income tax is voluntary or inapplicable. We simply do not invoke the Sixteenth as the basis for any status or claim set out on this site.
Taxes
Why We refrain: The federal income tax is established Law, enacted under the Sixteenth Amendment and enforced by the Internal Revenue Service. This project does not assert that the tax is inapplicable, voluntary, or unlawful, and it does not advise anyone to stop paying taxes or to violate any statute. The historical records below are provided for the study of the monetary system's origins.
Supporting Documents
The following primary records ground the study above. Copies will be added to this page for you to read directly.
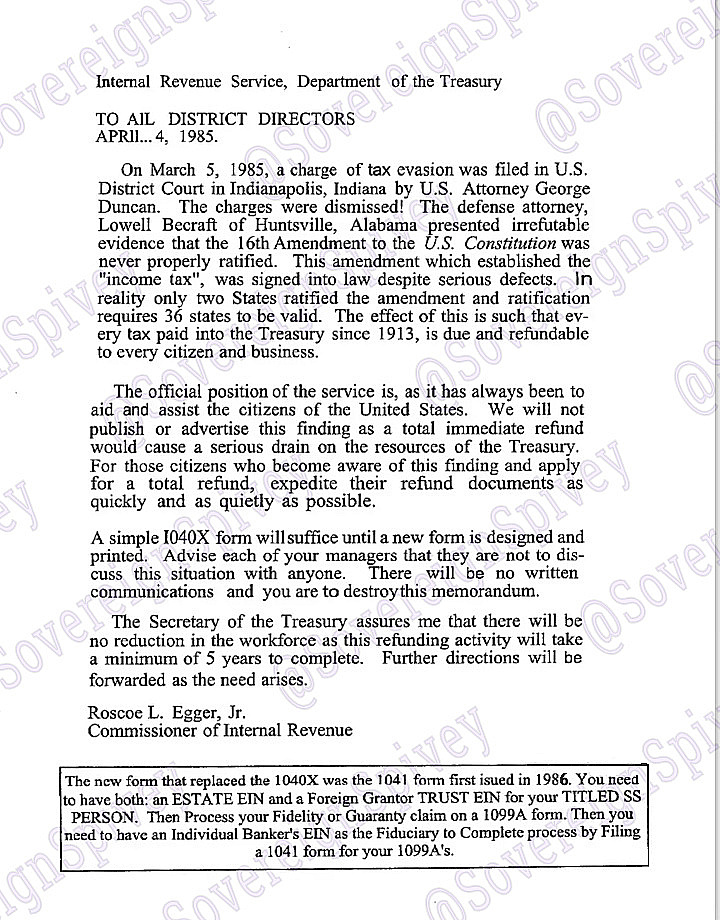
- 1. IRS Department of the Treasury, Memo to All District Directors (April 4, 1985)Internal Revenue Service memo from Commissioner Roscoe L. Egger, Jr., regarding the 16th Amendment and tax-evasion charges dismissed in U.S. District Court, Indianapolis (March 5, 1985).
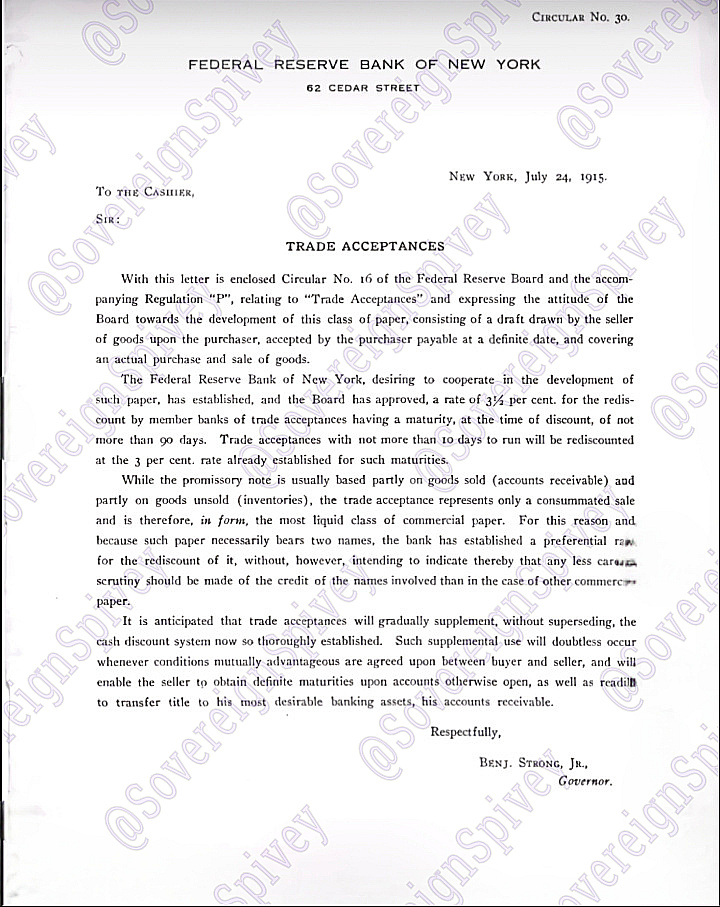
- 2. Trade Acceptances, Circular No. 30, New York (July 24, 1915)Federal Reserve Bank of New York circular from Governor Benj. Strong, Jr., enclosing Circular No. 16 and Regulation "P" on the definition and rediscount of trade acceptances.
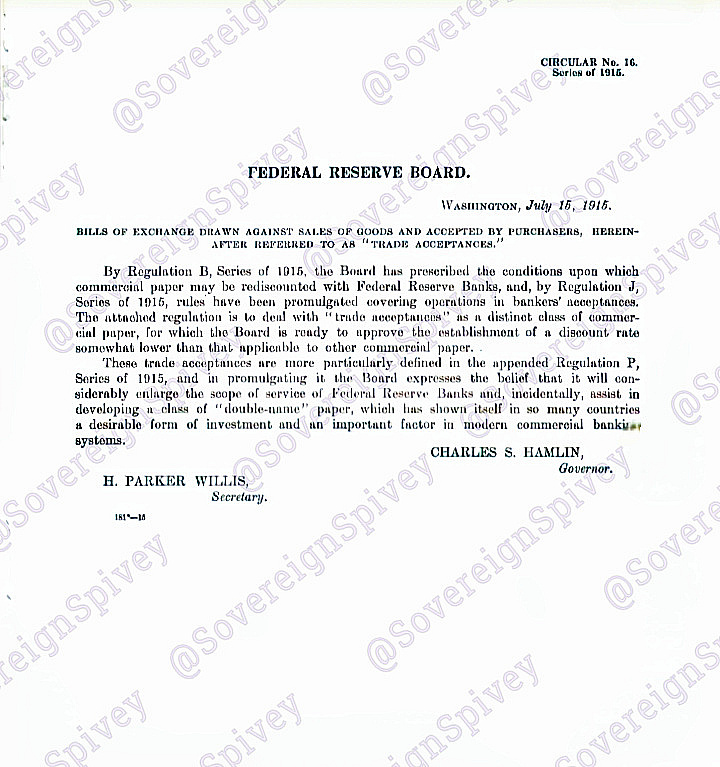
- 3. Regulation P, Circular No. 16, Federal Reserve Board, Washington (July 15, 1915)Federal Reserve Board circular signed by Governor Charles S. Hamlin and Secretary H. Parker Willis, promulgating Regulation P on trade acceptances as a distinct class of commercial paper.
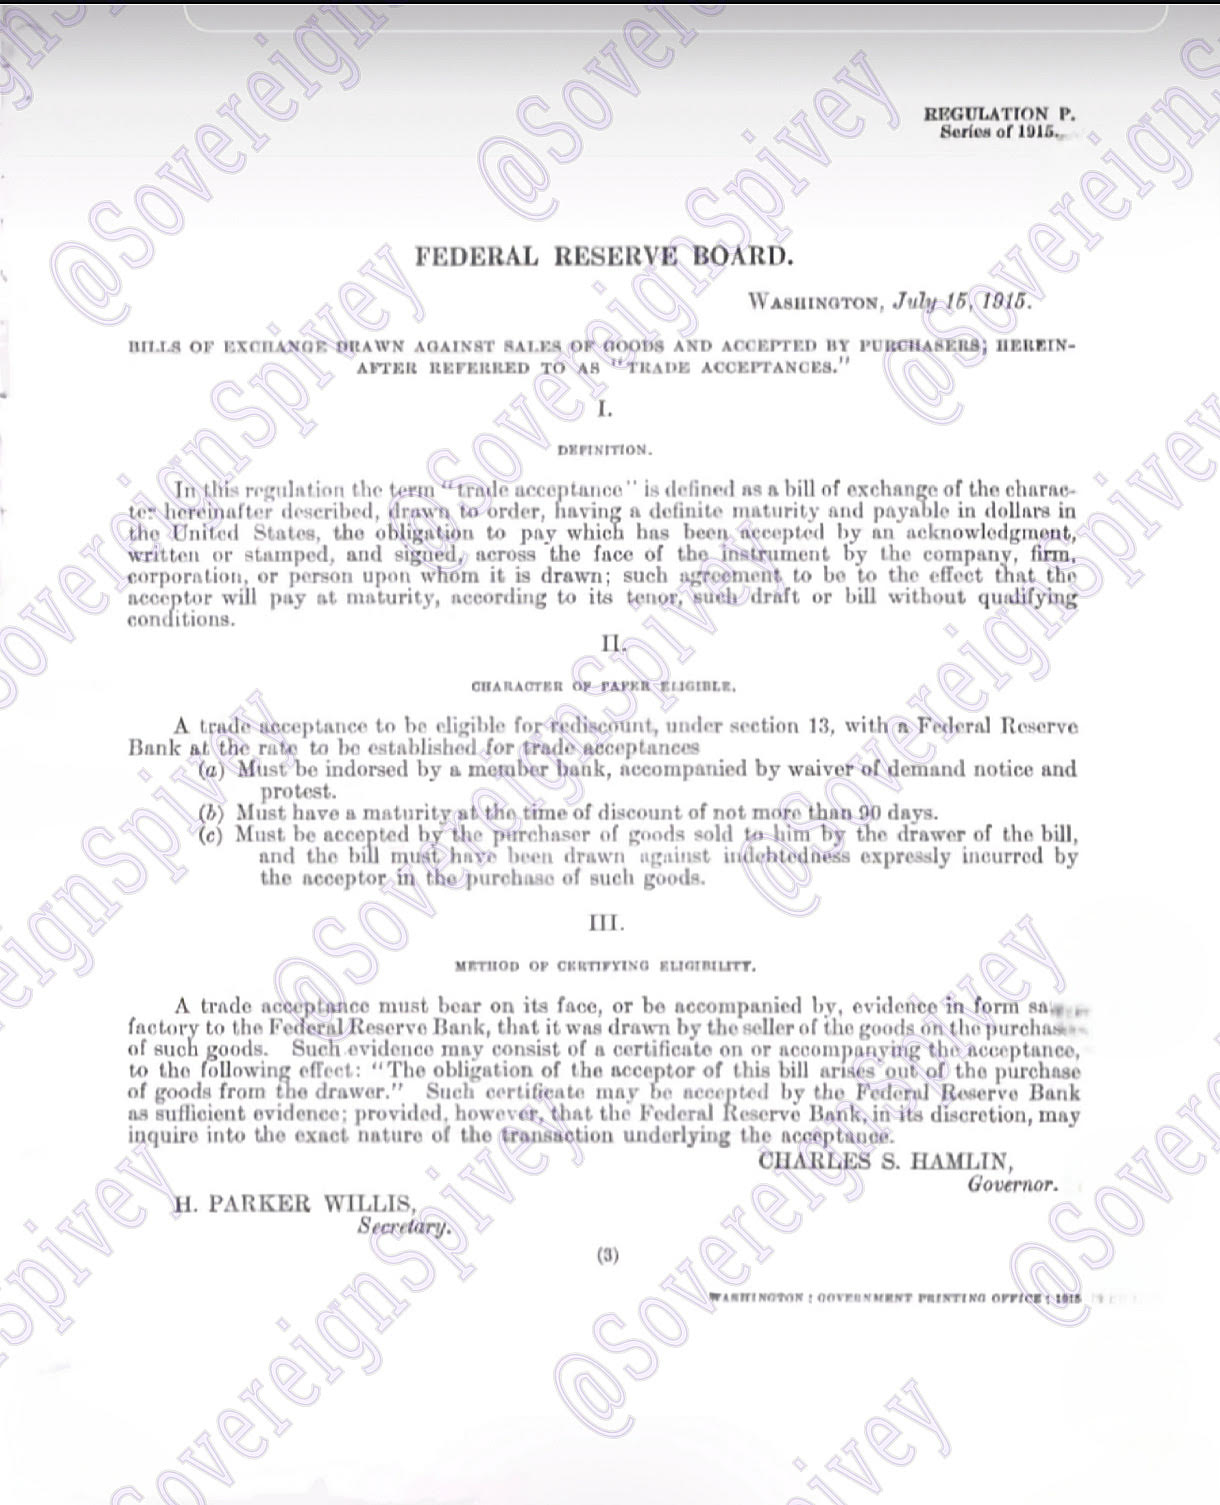
- 4. Regulation P, Series of 1915, Federal Reserve Board, Washington (July 15, 1915)The text of Regulation P itself, defining the "trade acceptance" and setting the conditions for rediscount of trade acceptances with a Federal Reserve Bank under section 13, signed by Governor Charles S. Hamlin and Secretary H. Parker Willis.
Other Claims We Refrain From
Additional claims, statutes, and theories that this project does not invoke will be listed here as the study continues.